
STAFF WRITER
Capricorn Group Limited has recorded profit after tax of N$1.87 billion , marginally down by 6.4%, their latest audited annual results for the year ended 30 June 2026 released on Thursday shows.
As a result the group declared a final ordinary dividend of 77 cents per share., together with the interim ordinary dividend of 58 cents per share, this brings the total ordinary dividend for the 2026 financial year to 135 cents per share.
The group said the profit comes amid a challenging operating environment, especially in Botswana and a disciplined balance-sheet management, robust capital and liquidity levels, and continued growth in diversified income streams.
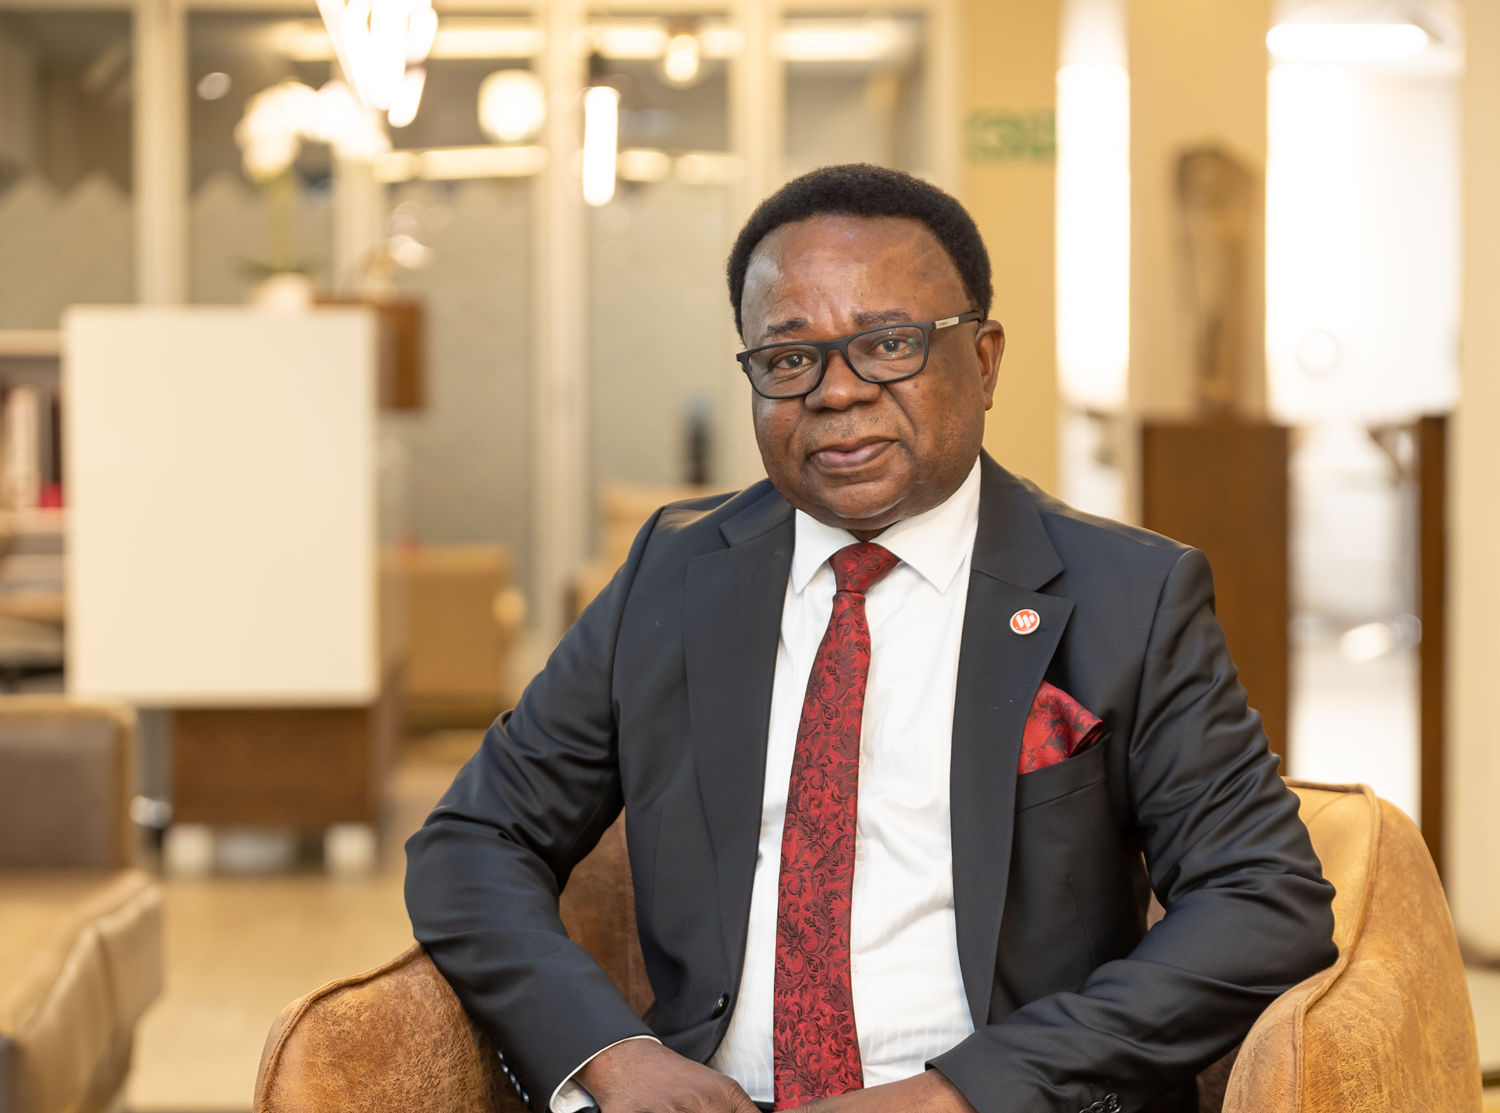
Commenting on the Group’s results, Group Chief Executive Officer David Nuyoma said the performance demonstrates the resilience of their diversified business model, the quality of our people and the strength of our financial foundation.
“ In a challenging operating environment, we strengthened our balance sheet, invested in future capabilities and continued to create meaningful value for our stakeholders.
“Through intentional collaboration across the Group and disciplined execution of our strategy, we are well positioned to support our customers, communities and economies, capture emerging opportunities across our markets, and deliver sustainable long-term value,” he said”
Other key indications in the group’s results showed basic earnings per share of 343.7 cents, down 6.4%, net asset value per share of 2,277 cents, up 6.7%, non-interest income of N$2.62 billion, up 8.3%, contributing 47.7% of operating income.
The group also saw total assets of N$75.3 billion, up 3.9%, deposits of N$56.22 billion, up 6.3%, capital adequacy ratio of 19.4% (2025: 18.1%) and total ordinary dividend of 135 cents per share, unchanged from 2025.
Despite these headwinds, prudent capital allocation, focused execution and strong financial fundamentals continued to create shareholder value. Net asset value per share increased by 6.7% to 2,277 cents, while the consolidated loan-to-funding ratio improved to 83.6% from 88.8%. The Group’s total risk-based capital adequacy ratio strengthened to 19.4%, well above the regulatory minimum of 12.5%.
Capricorn Group said Namibia’s emerging oil and gas sector, renewable energy developments and other growth sectors present significant long-term opportunities for the Group and its stakeholders.
“ While geopolitical uncertainty and uneven economic conditions are expected to continue shaping the operating environment, Capricorn Group is well-positioned to respond with agility and discipline,” the group said in a statement..
The Group’s diversified business model continued to provide resilience through the interest-rate cycle. Net interest income moderated by 1.9% to N$3.33 billion, while non-interest income increased by 8.3% to N$2.62 billion, supported by transactional income, trading revenue and asset-management fees.
“Diversified earnings streams continued to provide stability through the economic cycle. Non-interest income increased to nearly half of operating income, reducing dependence on interest-rate-driven earnings and demonstrating meaningful progress in the Group’s diversification strategy,” the group said in a statement.
Capricorn Group also saw non-interest income contributing 47.7% of operating income, exceeding the Group’s 45% target and underscoring the progress of its diversification strategy.
On the other hand, return on equity was 15.6%, compared with 18.2% in 2025.
The Group said operating expenses increased by 7.6% to N$3.27 billion as they continued to invest deliberately in its people and digital transformation agenda. These investments in technology, critical skills, operational efficiency and customer experience are building capabilities for sustainable future growth.
The results also indicated that Credit impairment charges increased to N$457 million from N$315 million and were the principal factor affecting earnings.
On the other hand Gross loans and advances were N$51.5 billion, compared with N$52.5 billion in 2025, reflecting softer loan demand in Botswana and lower loan uptake at Entrepo following the discontinuation of the automated Payroll Deduction Management System.
COMMENTS